A wrong credit limit can distort the utilization ratio shown by a credit report. First compare the bureau's date-updated field with the issuer's statement
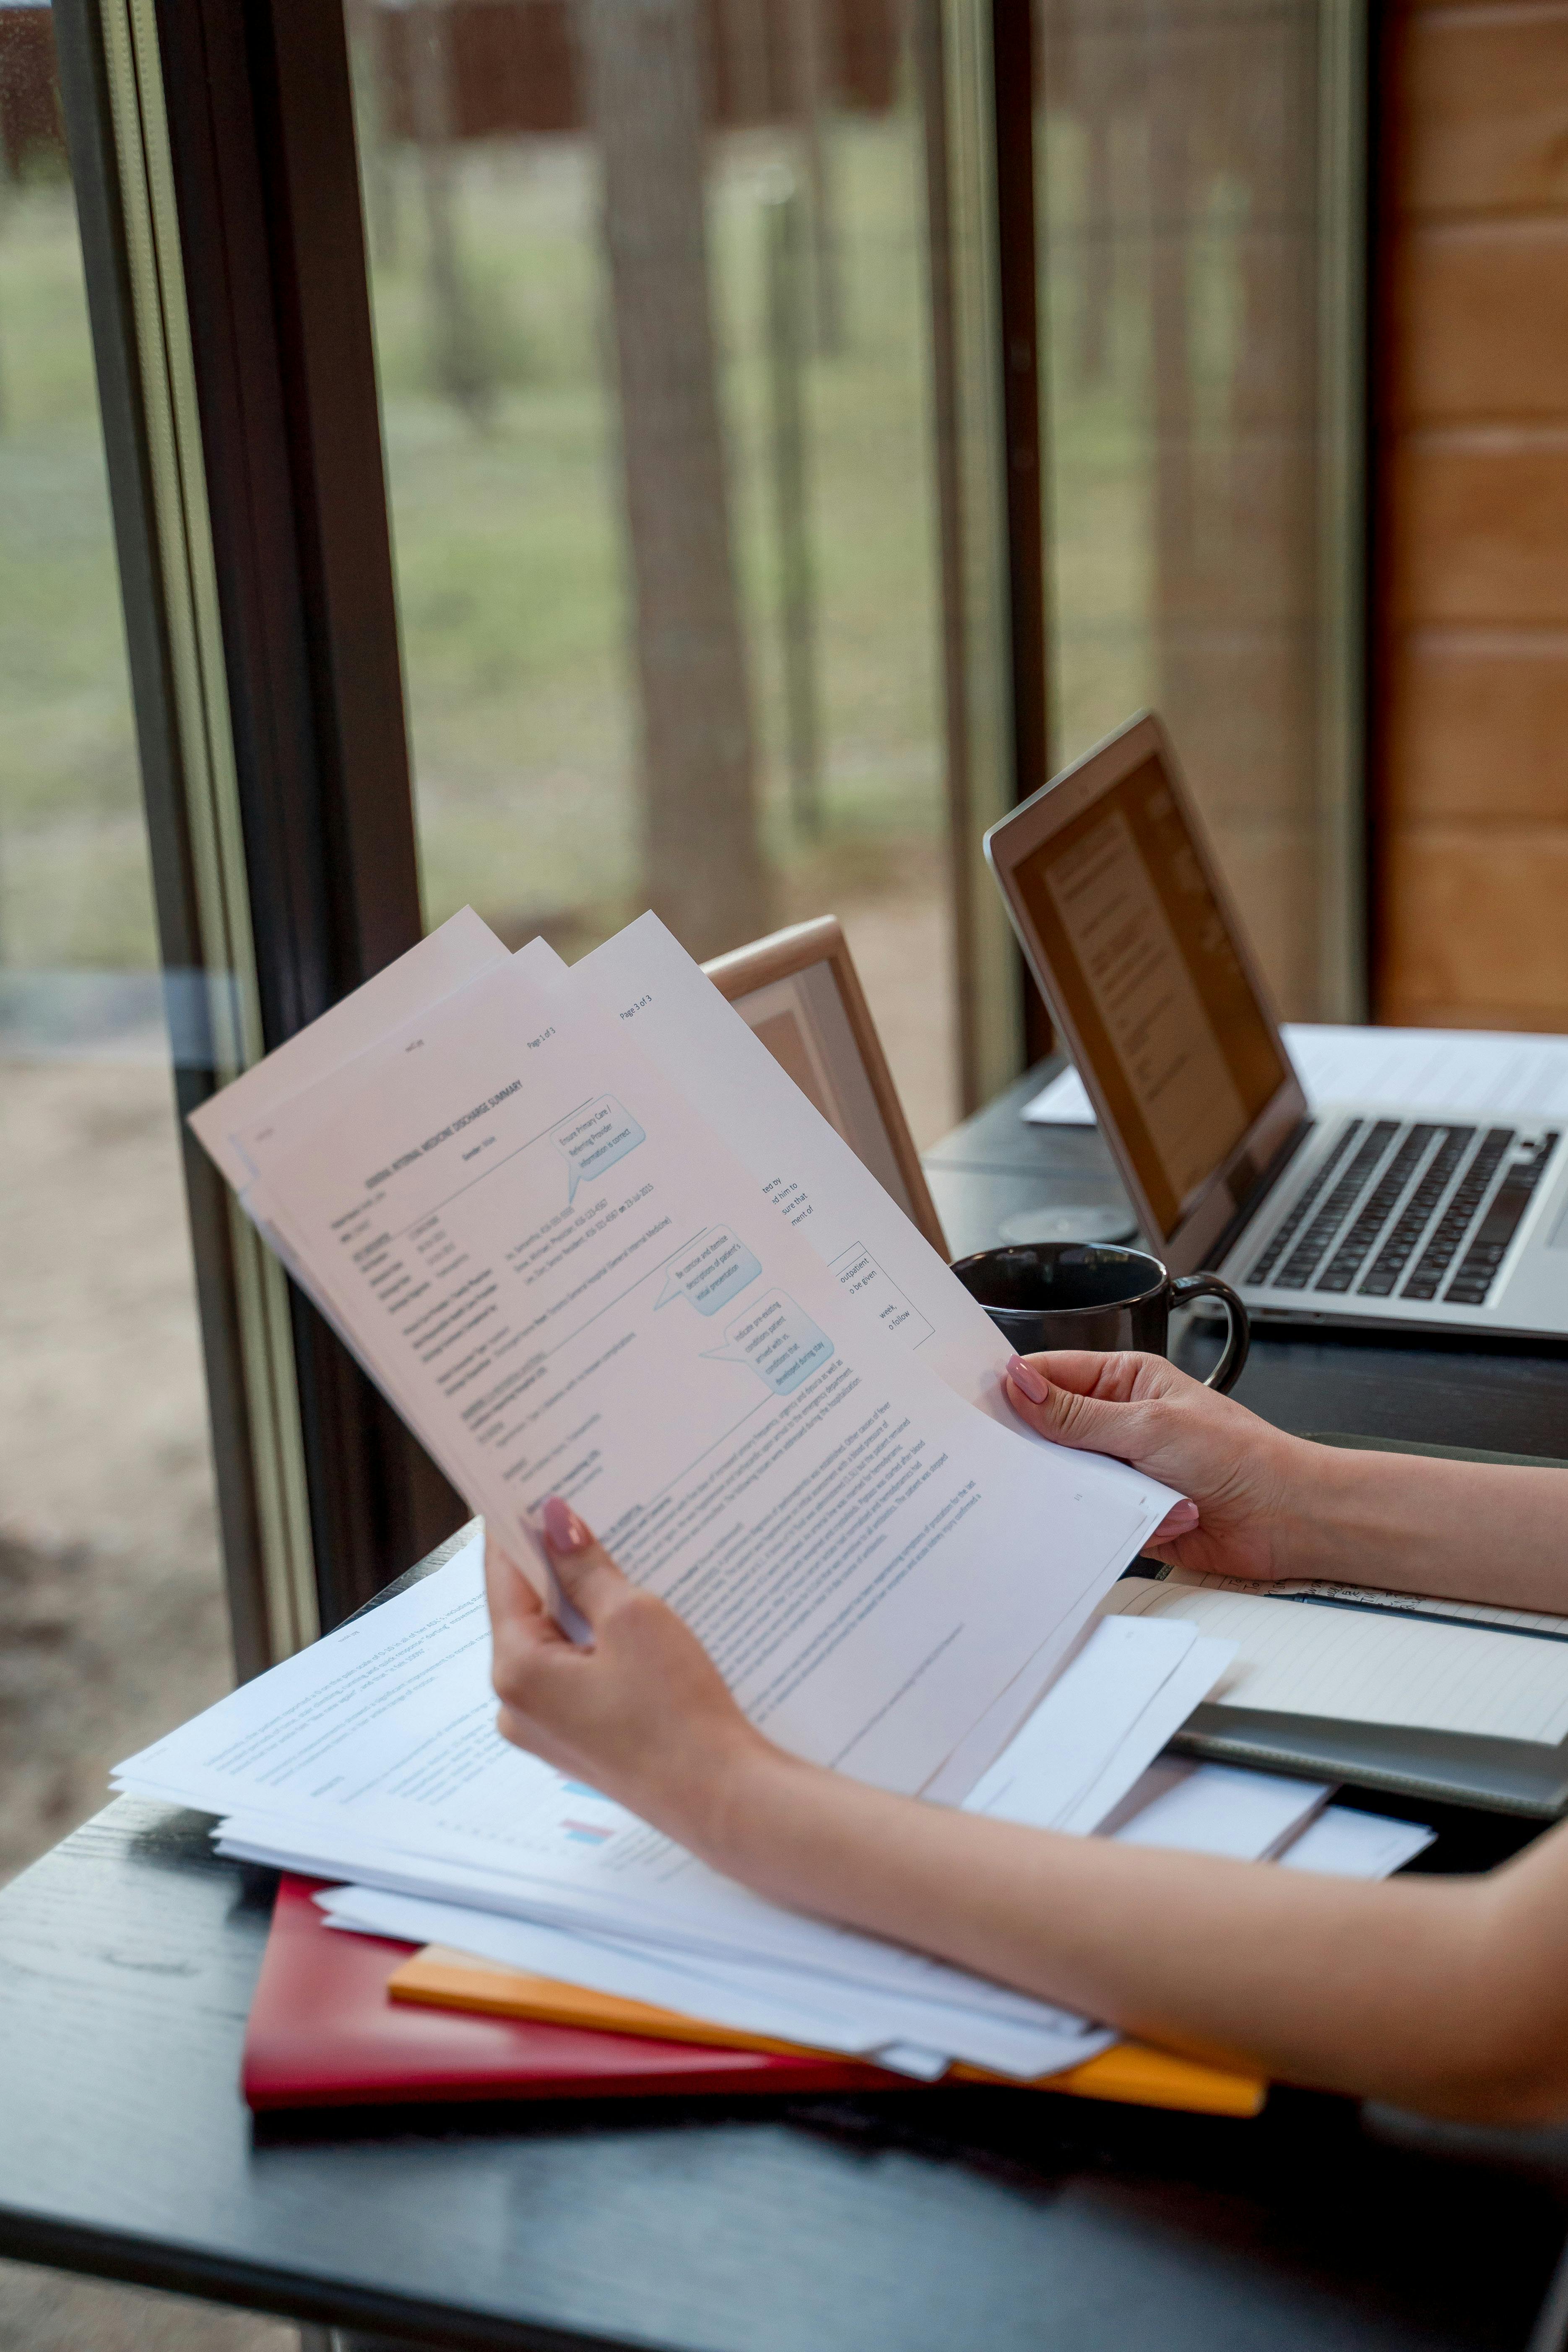
A wrong credit limit can distort the utilization ratio shown by a credit report. First compare the bureau's date-updated field with the issuer's statement or notice showing the limit effective at that time.
Check the underlying records
Review each bureau separately. A credit-line reduction, a reporting lag, an omitted limit, and an incorrect furnished limit require different responses. Today's app display may reflect a change that happened after the report was updated.
Take the next step
If the limit was wrong for the reporting date, request a correction from the issuer and dispute the specific field with each affected bureau. Attach a dated statement or notice. Save both your submission and the later report.
Know the limits
If the issuer actually changed the limit, a reporting dispute will not restore it. Consider your balance and payment plan, and avoid assuming a particular score change.
Further reading
https://www.consumerfinance.gov/ask-cfpb/what-are-common-credit-report-errors-that-i-should-look-for-on-my-credit-report-en-313/
Get Safesky's DIY credit repair guide
Start with the free A-to-Z PDF and use its steps to organize your credit records.
This article is general information, not legal or financial advice. Results vary by credit profile.