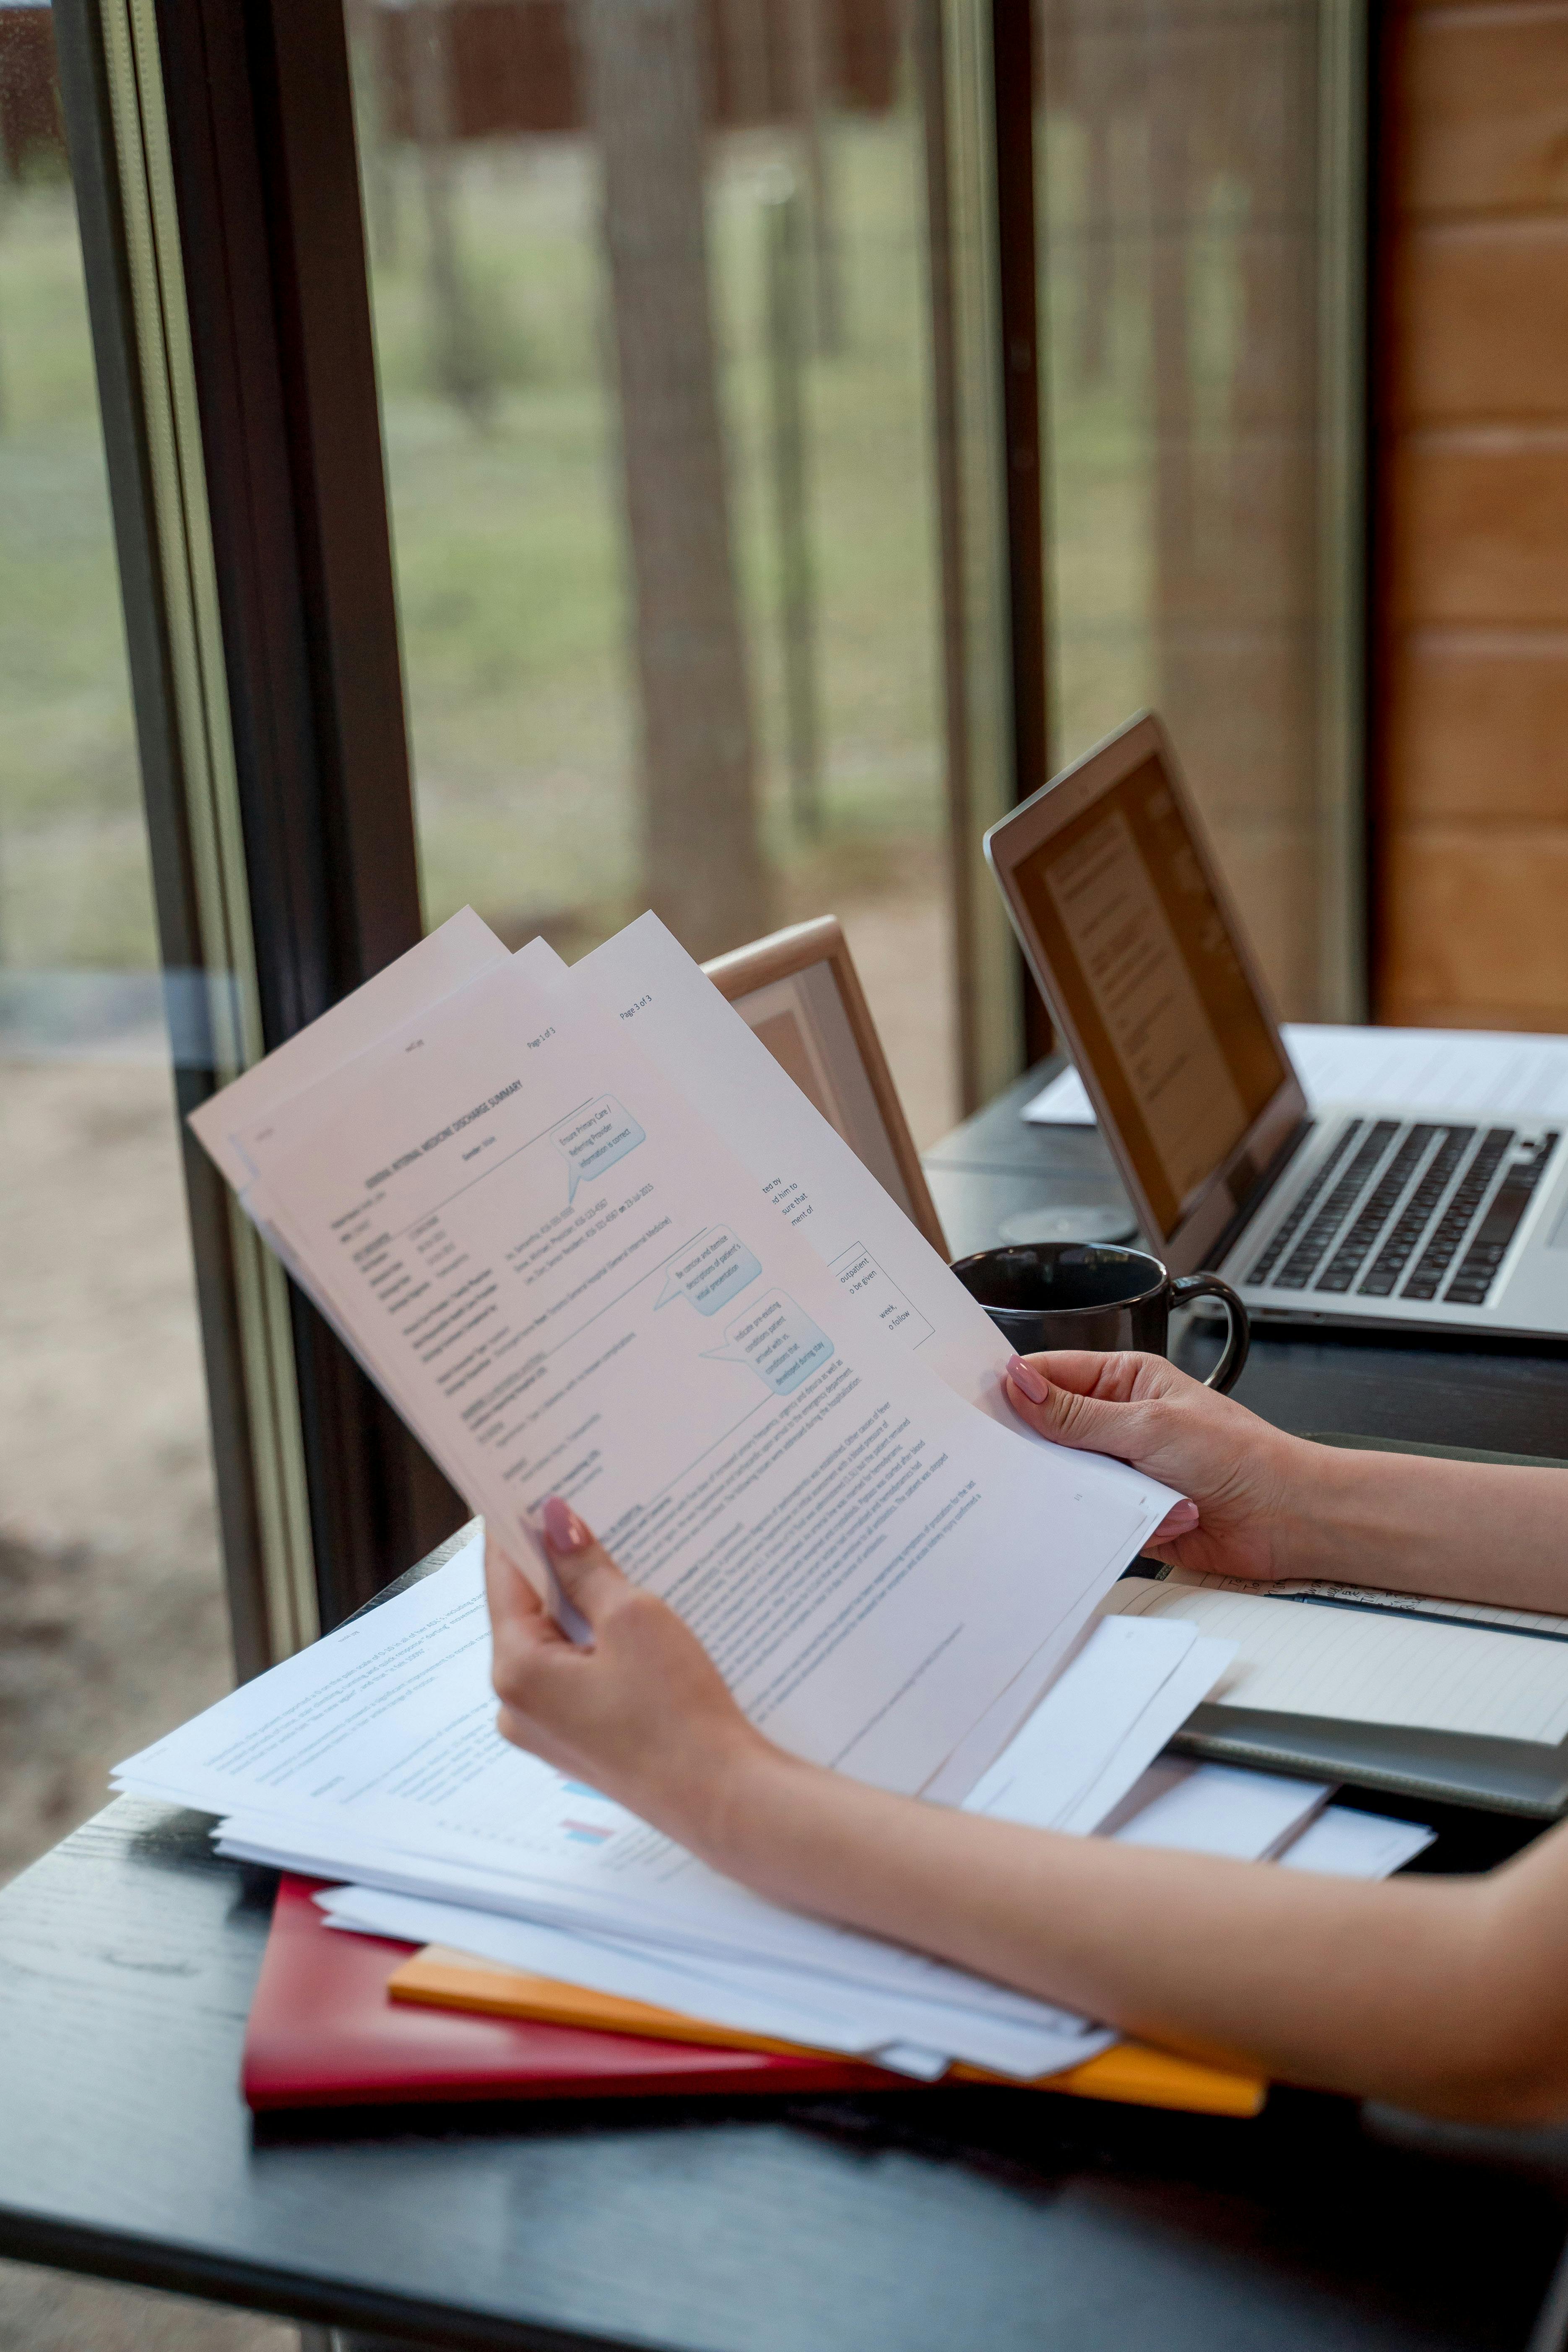
A practical half-hour routine for checking report accuracy, upcoming payments, and a realistic credit goal without chasing a promised score.
Set aside 30 minutes and gather your latest credit reports, card statements, loan statements, and calendar. The goal is to identify one action you can take, not to predict an exact score.
Minutes 0–10: inspect the reports
Check names, addresses, accounts, balances, limits, payment-history months, collections, and unfamiliar inquiries. Write down the bureau and date updated for any questionable entry. A current app balance may differ from an older furnished snapshot.
Minutes 10–20: protect payments and cash flow
List each due date and minimum payment for the next month. Confirm any autopay is funded and has actually posted. If card debt carries interest, calculate what you can pay above the minimum without missing essential expenses.
Minutes 20–30: choose one next step
For a documented error, organize the report page and supporting records and contact both the affected bureau and the furnisher. For accurate high balances, model a payoff scenario at https://calculator.safeskyconsulting.com/. For a report error, Safesky's tool at https://disputes.safeskyconsulting.com/ can help structure your facts. Neither tool guarantees a score change.
Official guidance
https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/ and https://consumer.ftc.gov/articles/free-credit-reports
Get Safesky's DIY credit repair guide
Use the free A-to-Z PDF to organize your credit plan and records.
This article is general information, not legal or financial advice. Results vary by credit profile.