
A practical system for organizing credit reports, dispute evidence, submissions, delivery records, responses and verified corrections without losing the paper trail.
A credit dispute can fail for a simple reason that has nothing to do with whether you are right: the evidence is scattered. One screenshot is on your phone, a statement is buried in email, a confirmation number was never saved, and the updated report replaces the version that showed the error. When the result arrives, you cannot tell what was investigated, what changed, or what to send next.
A dispute evidence file solves that operational problem. It is a dated, issue-by-issue record of the report, the specific error, the documents supporting your position, every submission, proof of delivery or portal confirmation, every response, and the final verification. It does not make inaccurate claims stronger, and it does not create a right to remove accurate negative information. It makes a legitimate accuracy dispute clear, traceable, and easier to evaluate.
Why recordkeeping matters in a credit dispute
The Federal Trade Commission advises consumers to identify each mistake, explain why it is wrong, include copies of supporting documents, mark the relevant report entries, and keep records of everything sent. The Consumer Financial Protection Bureau provides separate sample-letter instructions for disputes to a consumer reporting company and to the business that supplied the information.
Federal law also requires consumer reporting agencies to review and consider relevant information submitted by the consumer during a reinvestigation. That makes organization more than an administrative preference: your file determines whether you can present the relevant facts in a focused way and later show what information was available to the recipient.
Recordkeeping is especially important when an error appears at more than one bureau, an account has been sold or transferred, the response says “verified,” information reappears, or an application is pending. Without dated before-and-after reports, it is easy to confuse a balance update with correction of the disputed field.
Start with a case index, not a dispute letter
Before writing, create a case index with one row for each distinct issue. Do not treat an entire credit report as one dispute. A wrong late-payment month, an account that is not yours, an incorrect balance, a duplicate collection, and an obsolete address are different factual questions and may require different evidence.
- Issue number and short name, such as TU-01 Wrong May 2025 late payment.
- Credit bureau or other reporting company displaying the issue.
- Furnisher, collector, servicer, or public-record source associated with it.
- Account identifier exactly as shown on the report, using only enough digits to distinguish it securely.
- The field currently reported and the field you believe is correct.
- Why you believe it is inaccurate, incomplete, duplicated, obsolete, or not yours.
- Documents that support the correction.
- Submission date, method, recipient, confirmation, response deadline estimate, and result.
- Date the corrected report was obtained and independently checked.
This index becomes the control page for the file. It prevents duplicate submissions, shows which bureaus display the same problem, and separates unresolved issues from corrected ones. If several issues rely on the same statement, reference that exhibit rather than making multiple uncontrolled copies.
Folder structure for a paper or digital case file
A simple structure works better than a complicated app. Use a secure folder for the overall case, then a subfolder for each issue. Within each issue, use numbered sections so the chronology is obvious. A paper binder can follow the same structure with dividers.
- 00 Case index and contact log.
- 01 Original credit reports.
- 02 Issue summary and timeline.
- 03 Supporting evidence.
- 04 Draft and final dispute submissions.
- 05 Delivery records and portal confirmations.
- 06 Bureau and furnisher responses.
- 07 Updated reports and field-by-field verification.
- 08 Escalation records, complaints, adverse-action notices, or legal correspondence.
File names should explain what the document is without exposing unnecessary personal information. A pattern such as 2026-09-22_Experian_Report_Before.pdf is clearer than IMG_4821.jpg. Put the date first in year-month-day format so files sort chronologically.
Do not store full Social Security numbers, passwords, identity documents, and unredacted bank statements in an unsecured shared drive. Use device encryption, strong access controls, backups, and secure transmission methods. Keep a private master copy and create a redacted submission copy containing only what the recipient needs.
Build the baseline report set
Obtain and save reports from all three nationwide credit reporting companies through the federally authorized source, AnnualCreditReport.com. The FTC explains that checking reports is necessary to identify whether information is accurate and complete. Save the full report, not only the page with the disputed account, because personal identifiers, inquiries, remarks, and related accounts may help diagnose the error.
Label each report with the bureau and retrieval date. Record the report number and any access confirmation. If a lender or landlord supplied a different report or adverse-action notice, save that separately; a screening report or lender disclosure may not be identical to the consumer disclosure you retrieved.
Never edit the baseline PDF or overwrite it with a later report. Make an annotated working copy and keep the original unchanged. Circle or highlight the disputed fields on the copy you submit, while preserving the clean original for comparison.
Write an issue summary that an investigator can follow
The issue summary should fit on one page when possible. State the account, field, reporting period, reported value, correct value, and requested action. Then provide a short chronology and an exhibit list. Avoid legal-sounding accusations that the documents do not support.
For example: “The report shows a 30-day late payment for May 2025. The May statement lists a May 22 due date; Exhibit B shows the payment posted May 18; Exhibit C is the creditor’s secure message confirming receipt. Please correct the May 2025 payment status to current.” That is more useful than “delete this illegal account immediately.”
If you do not know the correct value, say what you can prove. You might state that an account does not belong to you, that the balance differs from the attached payoff statement, or that the same debt appears twice. Do not invent a replacement value merely to make the request look complete.
Choose evidence for the exact field
Evidence quality is about relevance, not volume. A bank statement may show that money left your account but not how a creditor applied it. A creditor receipt may show a transaction but not the governing due date. Pair documents so they establish the complete timeline.
- Wrong payment status: billing statement, due date, payment confirmation, bank record, creditor ledger, and any accommodation agreement.
- Wrong balance or limit: dated statement, payoff or settlement confirmation, account ledger, and the report showing the conflicting value.
- Account not yours: report page, identity documentation requested by the bureau, creditor records available to you, and identity-theft materials when the facts support that path.
- Duplicate collection: both report entries, original creditor and collector information, account numbers, balances, dates, and transfer or validation records.
- Wrong ownership role: account agreement or creditor confirmation distinguishing individual, joint, co-signer, and authorized-user status.
- Obsolete or misdated item: documents establishing the relevant dates, together with the report’s dates and status fields.
Use copies, not original documents. Redact unrelated transactions and account numbers while leaving enough visible to connect the evidence to you, the account, the relevant date, and the disputed fact. Label each exhibit—A, B, C—and cite those labels in the issue summary.
Create a clean submission package
A well-ordered package usually contains a cover or dispute letter, a marked copy of the report, the issue summary, the supporting exhibits, and identity or address documentation requested by the recipient. The CFPB’s sample letters are useful starting points, but they should be adapted to the actual facts.
If several unrelated issues are sent together, separate them clearly and provide an exhibit map. A large undifferentiated packet can make the investigation harder. Consider separate submissions when the issues involve different furnishers, different consumers, identity theft, or substantially different evidence.
Before sending, make a locked final copy of exactly what will be transmitted. Do not rely on a draft that may differ from the mailed letter or portal upload. Check that every referenced exhibit is present, legible, correctly oriented, and free of accidental data from another case.
Mail, online portal, or phone: preserve the right record
The best channel depends on the issue and the documentation. Online portals can be fast and provide tracking, but may constrain explanations or file types. Mail can accommodate a detailed packet and physical delivery record. Phone disputes may be practical for simple matters, but they make it especially important to record the date, representative, reference number, and exact issue described.
The FTC recommends keeping copies of everything sent and, for mailed disputes, suggests certified mail with a return receipt so the consumer has a record of receipt. Before mailing, confirm the current dispute address from the credit report or the company’s official instructions; addresses and processing channels can change.
For an online dispute, save the confirmation page, confirmation email, uploaded filenames, and a PDF or screenshot of the final submission. A portal status alone may not preserve the narrative and evidence you supplied. For phone contact, follow up in writing when the issue is complex.
Track the investigation without miscounting deadlines
Under 15 U.S.C. § 1681i, a consumer reporting agency generally must conduct a reasonable reinvestigation within 30 days after receiving a consumer’s dispute. The period can be extended by up to 15 days in certain circumstances when relevant information is submitted during the initial period. Other rules and facts can affect timing, so treat your calendar as a management tool, not individualized legal advice.
Record the received date separately from the sent date. Add reminders before and after the expected response window. If you submit additional evidence, log what was sent and when because it may affect the investigation period. Do not assume silence means deletion or victory.
Keep one contact log for calls, secure messages, chats, and letters. Include the company, department, representative, time, reference number, what you asked, what was said, and the promised next step. Write factual notes immediately rather than reconstructing them weeks later.
Read the result as a data comparison
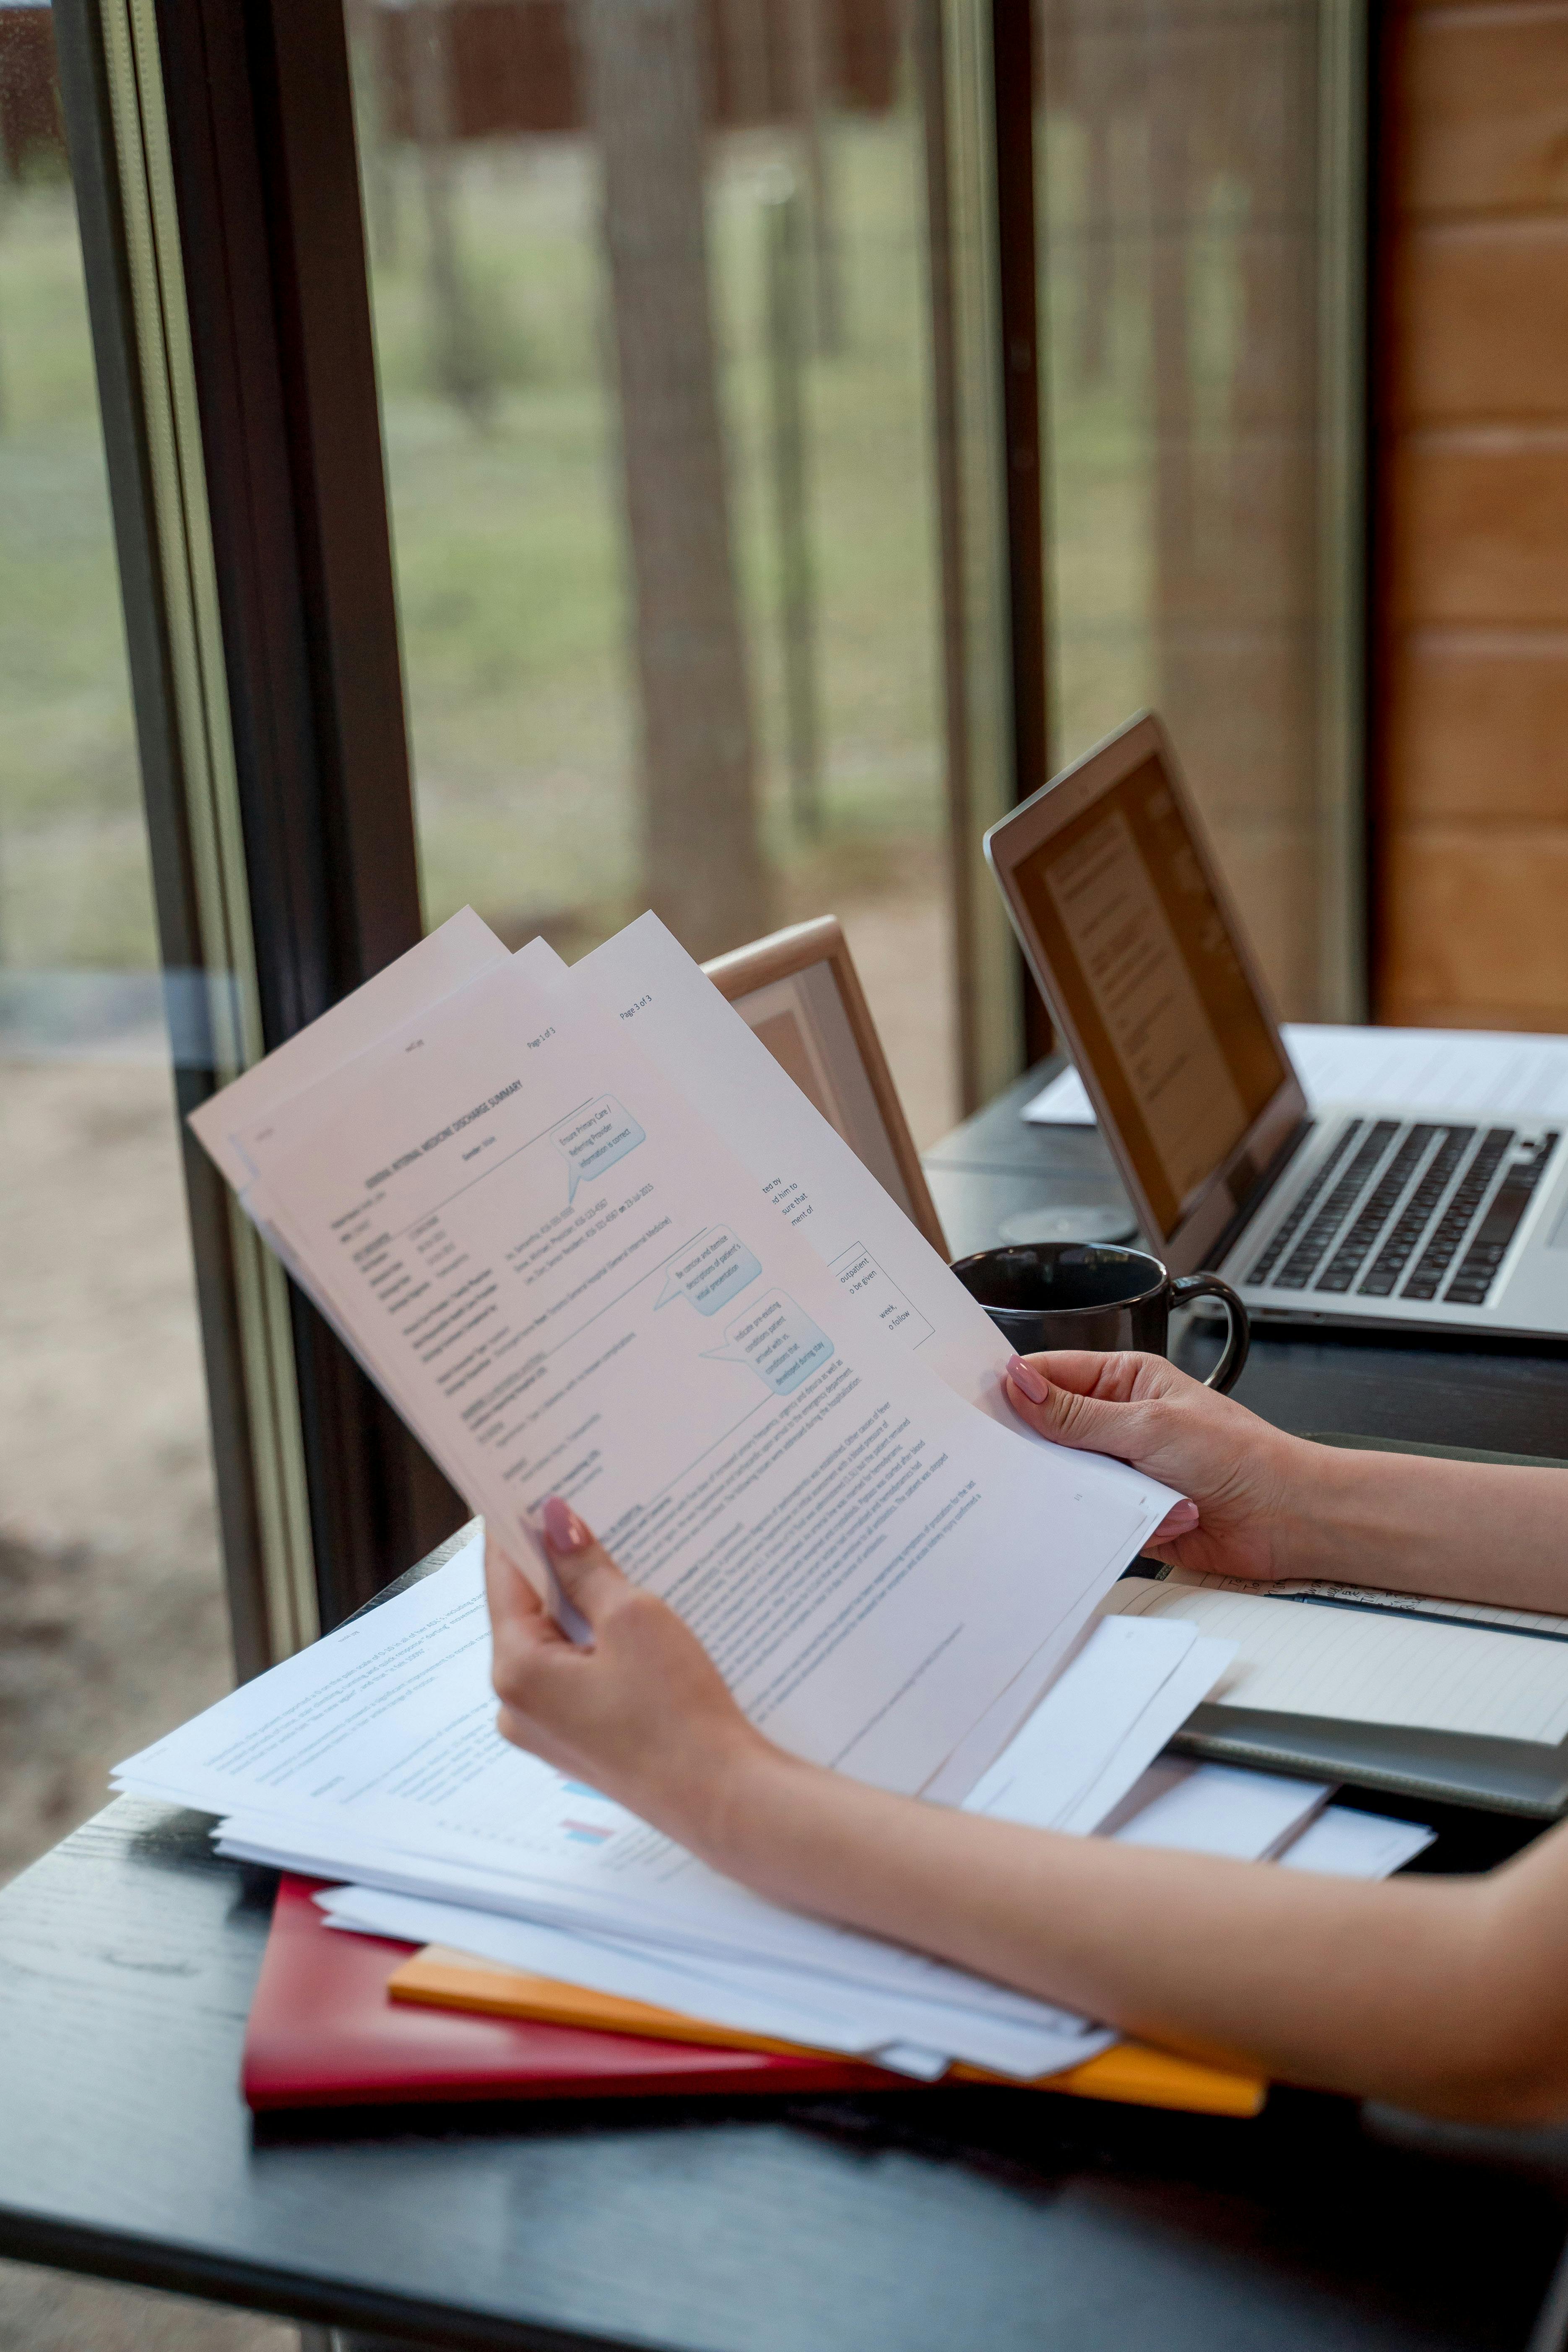
When the result arrives, save the response and the complete revised report. “Updated” does not tell you which field changed. Compare the original and new report using a verification checklist: payment history, ownership, status, balance, limit, past-due amount, dates, remarks, personal information, and whether the account remains.
Add a result row to the case index: corrected, partially corrected, unchanged, deleted, reinserted, or needs clarification. Record the response date and link it to the corresponding submission. If the issue appears on multiple bureaus, verify each one independently.
If information was deleted, preserve the before report, result, and after report. Federal law addresses reinsertion and notice requirements, and the record will matter if the item returns. If a correction affected an active application, ask the decision-maker what refreshed report or documentation is required.
What to do after a verified or incomplete result
A response stating that information was verified is not necessarily proof that your evidence was wrong. Review whether the response addressed the field you disputed and whether your attachments were transmitted and considered. Do not simply resend the identical package repeatedly.
Add new, relevant information: a creditor ledger, clearer statement, written admission, identity-theft report, or explanation resolving a mismatch. The FCRA gives consumers the ability to request a description of the procedure used to determine accuracy and completeness after a reinvestigation. The CFPB also accepts consumer complaints when ordinary dispute channels do not produce an adequate response.
Escalation should preserve the same case number and chronology. Include the original report, original submission, delivery proof, response, revised report, and the new evidence. That allows a complaint reviewer or attorney to understand the history without guessing.
Common recordkeeping mistakes
- Overwriting the original credit report with an updated version.
- Sending original documents that cannot be replaced.
- Using one generic letter for unrelated accounts and fields.
- Saving screenshots without the URL, date, report number, or surrounding context.
- Submitting through a portal without saving the final text and uploaded files.
- Keeping confirmation numbers only in temporary browser tabs or text messages.
- Redacting the very date, name, or account fragment needed to connect the evidence.
- Including full unrelated bank activity or sensitive data that the recipient does not need.
- Treating a score change as proof that the disputed information was corrected.
- Discarding records as soon as one bureau changes an item.
Costs and practical alternatives
The core dispute process and official report resources are generally available without paying a credit-repair company. Costs may include postage, copying, secure storage, credit monitoring, professional advice, and the time needed to collect records. Certified mailing options have fees that vary, so verify current prices directly with the carrier instead of relying on an old estimate.
A spreadsheet can manage the case index, while encrypted folders store documents. A paper binder may be easier for someone who works best with physical records. The right system is the one you can keep complete, secure, and chronological. Do not buy complex software merely because it promises automated deletions or guaranteed score changes.
When identity theft, litigation, a mortgage deadline, employment screening, repeated mixed-file errors, or substantial financial harm is involved, a qualified consumer-law attorney or appropriate counselor may be more valuable than additional templates. Organization helps that professional evaluate the case; it does not replace legal advice.
A final quality-control checklist
- Every issue has its own identifier and factual summary.
- The original reports are saved unchanged and dated.
- The disputed fields are marked on submission copies.
- Every claim points to a labeled, relevant exhibit.
- Only necessary personal information is included.
- The recipient and address or portal are verified from an official source.
- An exact copy of the final submission is saved.
- Receipt, confirmation, and response dates are logged.
- The updated report is compared field by field.
- Unresolved issues have a documented next step rather than a repeated generic dispute.
Sources and limitations
Primary and authoritative sources consulted: Federal Trade Commission, Disputing Errors on Your Credit Reports, https://consumer.ftc.gov/articles/disputing-errors-your-credit-reports ; Consumer Financial Protection Bureau sample dispute letters and instructions, https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/sample-letters-dispute-credit-report-information/ ; 15 U.S.C. § 1681i, https://www.law.cornell.edu/uscode/text/15/1681i ; AnnualCreditReport.com dispute information, https://www.annualcreditreport.com/filingADispute.action ; IdentityTheft.gov, https://www.identitytheft.gov/ ; and CFPB guidance for unresolved disputes, https://www.consumerfinance.gov/ask-cfpb/what-if-i-disagree-with-the-results-of-my-credit-report-dispute-en-1327/ .
This article provides general educational information, not legal, financial, or credit-repair advice for a specific situation. Laws, bureau procedures, addresses, portal features, carrier services, and your facts can change. Verify current instructions through official sources and consult a qualified professional when rights, deadlines, or material harm are involved.
Turn scattered documents into one usable case file
A strong dispute file does not need to be impressive. It needs to be complete, specific, secure, and easy to audit: one issue index, unchanged baseline reports, relevant exhibits, exact submission copies, delivery evidence, responses, and verified after-reports. That structure lets you act on facts instead of relying on memory when the next response arrives.
Build your dispute file with a clearer framework
Download Safesky Digital’s free Credit Repair A-to-Z PDF to pair this recordkeeping system with a step-by-step overview of reports, disputes, utilization and debt decisions.
This article is general information, not legal or financial advice. Results vary by credit profile.