
Learn how to distinguish a mixed credit file from identity theft, document unfamiliar accounts, limit immediate risk, dispute precisely and verify that corrections hold.
Finding an account, address, employer, inquiry, or collection that does not belong to you is not a normal credit-score problem. It is a data-identity problem. The wrong information may come from identity theft, a creditor’s reporting mistake, or a “mixed file,” where information associated with another consumer is matched to your credit file. Those possibilities overlap, but they do not call for exactly the same response.
The safest approach is to diagnose first, preserve evidence, and use the correction path that matches the facts. A generic online dispute that says only “not mine” may be too vague. On the other hand, filing an identity-theft report when you merely recognize a relative’s address or an old employer can send you down the wrong path. This guide explains how to separate the likely causes, limit immediate risk, build a precise record, and escalate when a correction does not hold.
What a mixed credit file means
A mixed file occurs when a consumer reporting system associates information belonging to one person with another person’s file or report. The people may have similar names, Social Security numbers with close digits, shared addresses, family relationships, or other overlapping identifiers. A mixed file is not itself proof that anyone stole your identity. It can be a matching or data-quality failure.
Identity theft is different. It involves someone using your personal information without permission, often to open an account, obtain services, make purchases, or otherwise commit fraud. A report can contain an unfamiliar account because of identity theft, but an unfamiliar item can also result from a creditor’s mistake, an authorized-user relationship, a sold or transferred account, or a mixed file.
The distinction matters because federal law provides a special blocking process for information resulting from identity theft. A routine accuracy dispute, by contrast, asks a consumer reporting company to reinvestigate information that is inaccurate, incomplete, or cannot be verified. Both paths require specific identification of the information, but an identity-theft block requires additional documents and statements.
Signs that point toward a mixed file
- The report contains another person’s address, middle name, employer, or phone number together with accounts you do not recognize.
- Several unfamiliar accounts appear to belong to the same other person rather than reflecting isolated fraudulent applications.
- The incorrect information repeatedly returns after individual accounts are corrected.
- A lender receives a report that seems to combine your history with a relative’s or another consumer’s history.
- The problem appears on one bureau’s report but not the others, or the identifying information differs materially among the three.
- A creditor confirms that its own customer has a different date of birth, address, or identifying information from yours.
None of these signs proves the cause. Treat them as clues. A mixed file may still expose you to denials, higher prices, collection contacts, or screening problems, so it deserves prompt action even when no fraud occurred.
Signs that point toward identity theft
- A new account, inquiry, purchase, or collection follows a lost wallet, data breach, phishing event, mail theft, or takeover of an online account.
- A creditor has an application, contact method, shipping address, or transaction history you did not create.
- You receive bills, collection notices, authentication messages, or account-change alerts for activity you did not authorize.
- Your legitimate account has unfamiliar charges or its mailing address, phone number, password, or authorized users changed.
- Multiple institutions report attempted accounts or transactions using your personal information.
Identity theft can occur without an obvious credit-report entry, and a report error can occur without identity theft. Review bank, card, telecom, utility, insurance, and government-benefit activity as well as the three nationwide credit reports. If there is active fraud, containment cannot wait for a credit dispute to finish.
First response: preserve the evidence before changing anything
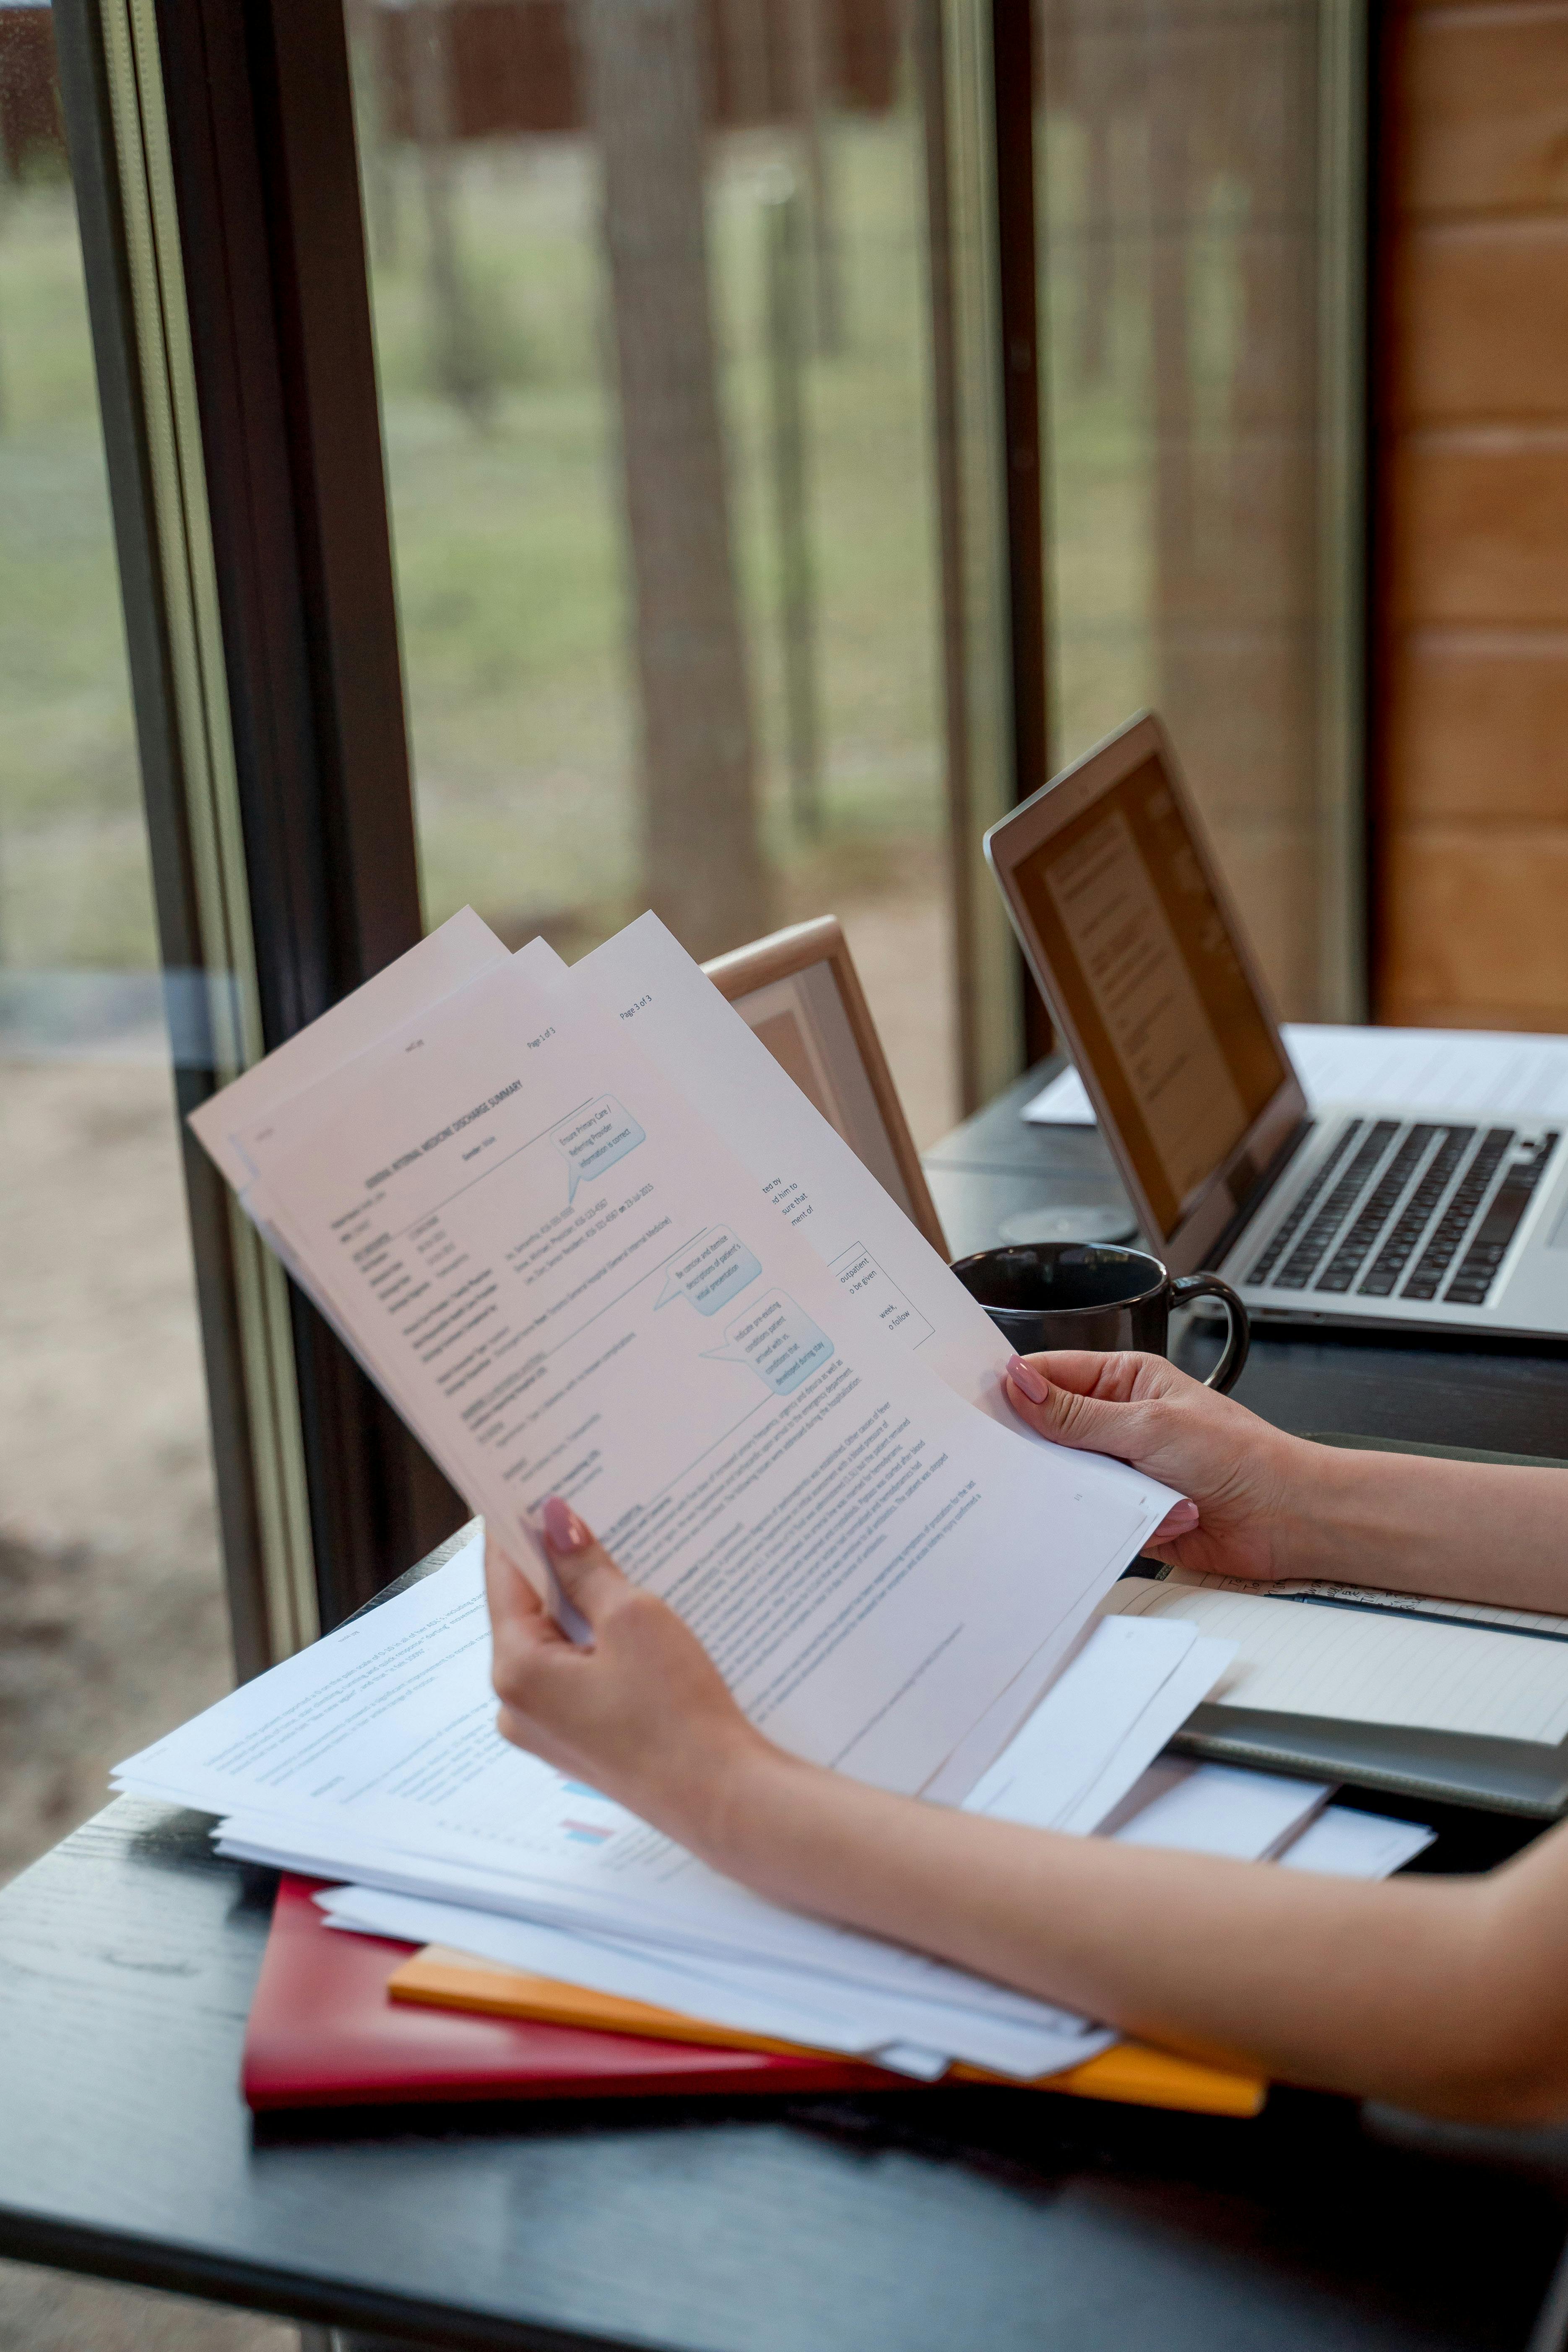
Save a complete copy of every report showing the problem, including the report date, report number, personal-information section, account details, payment history, inquiries, and remarks. Screenshots can help, but a full downloaded or printed report is more useful because the surrounding fields may reveal how the information was matched.
Create a one-page issue table. For each item, record the bureau, furnisher, account identifier, date opened, balance, address, inquiry date, and the exact field that is wrong. Mark whether the item appears on Equifax, Experian, TransUnion, or more than one. Do not combine ten different errors into a sentence such as “my whole report is wrong.”
Keep originals of identity documents, bank records, correspondence, and creditor records. Send copies through secure channels and redact unrelated data where appropriate. Log calls with the date, department, representative, reference number, and promised action. A clean chronology becomes important if the wrong information returns or a company claims it never received your evidence.
Limit immediate risk
If identity theft is possible, consider placing a free security freeze with each of the three nationwide credit reporting companies. A freeze restricts access to your credit file for many new-account decisions, but it does not correct existing information, stop misuse of current accounts, or block every type of transaction. You must contact each bureau separately to place and manage a freeze.
A fraud alert is different. An initial fraud alert generally tells businesses to take steps to verify your identity before opening new credit. According to the FTC, contacting one nationwide bureau to place an initial alert should cause that bureau to notify the other two. A freeze and fraud alert can coexist; neither substitutes for contacting affected creditors.
Change compromised passwords, enable stronger authentication, secure email and mobile accounts, and notify financial institutions about unauthorized activity. Do not include full Social Security numbers, passwords, or unnecessary medical or financial details in ordinary email. If physical mail is missing or redirected, address that problem as part of containment.
Choose the correct correction path
Use a routine accuracy dispute when the problem appears to be mistaken matching, wrong personal information, duplicate reporting, a creditor error, or another inaccuracy not caused by identity theft. Send a focused dispute to every consumer reporting company displaying the item and, when appropriate, to the business that furnished it.
Use the identity-theft blocking process when information resulted from identity theft and you can supply the required documentation. Under 15 U.S.C. § 1681c-2, a consumer reporting agency generally must block identified identity-theft information within four business days after receiving appropriate proof of identity, an identity-theft report, identification of the information, and a statement that the information does not relate to a transaction by the consumer. Exceptions allow a block to be declined or rescinded in specified circumstances, including material misrepresentation.
Do not label an item identity theft merely because you dislike or do not immediately recognize it. First check old account names, debt buyers, servicing transfers, authorized-user relationships, joint or co-signed obligations, and the creditor’s records. Filing a false report or making a material misrepresentation can create serious legal and practical consequences.
How to write a mixed-file dispute
Name the problem directly: “This report contains identifying information and accounts belonging to another consumer.” List the exact foreign identifiers and tradelines. State what belongs to you and what does not. If the other person is a relative, do not submit that person’s sensitive documents without authorization; explain the relationship and use your own records to prove your identity and history.
Ask for more than deletion of one account when the evidence suggests broader mixing. Request that the bureau separate the files, remove every identified item that does not belong to you, correct inaccurate personal identifiers, and use reasonable procedures to prevent the same information from being rematched. Keep the request factual rather than demanding a particular internal technical solution.
Include a copy of the relevant report pages with the errors clearly marked, proof of identity and address requested by the bureau, and documents showing the correct facts. The CFPB publishes sample letters and instructions for disputes to both consumer reporting companies and furnishers. Adapt them; do not send a form letter that fails to describe your actual mismatch.
What federal reinvestigation rules generally require
The Fair Credit Reporting Act’s reinvestigation provision generally gives a consumer reporting agency 30 days after receiving a dispute to conduct a reasonable reinvestigation, with a limited extension of up to 15 additional days when the consumer provides relevant information during the initial period. The agency must review and consider relevant information submitted by the consumer.
If information is found inaccurate, incomplete, or unverifiable, the statute requires deletion or modification as appropriate. It also addresses notice of results, reinsertion of deleted information, procedures to prevent reappearance, and the consumer’s ability to request a description of the reinvestigation procedure.
Timelines are not a promise that every problem will be resolved in 30 days. Identity verification, multiple furnishers, additional evidence, or a complaint may extend the practical process. Calendar every submission and response, but judge success by the corrected report—not merely by a portal status saying “completed” or “updated.”
Contact the furnisher without losing sight of the bureau
A creditor, collector, or other furnisher may be able to show whether it actually has an account linked to your identity. Ask for the application or account-opening records available to you, the addresses and contact details used, the dates, and the basis for associating the account with you. Avoid providing new personal information until you have verified whom you are contacting.
If the furnisher confirms a mismatch, request written confirmation and correction of reporting to every bureau it contacted. If the furnisher alleges identity theft, use the official recovery process and ask what fraud affidavit or supporting records it requires. Continue disputing with the bureau because correction in one company’s system does not guarantee that every report has changed.
How to verify the result
- Compare the revised report against the saved original field by field.
- Confirm that foreign names, addresses, employers, phone numbers, accounts, collections, and inquiries were addressed—not just one tradeline.
- Check all three bureaus even if the original error appeared on only one.
- Save the investigation result and the complete corrected report.
- Monitor for reinsertion or rematching during the following months.
- If an active loan, rental, insurance, or employment decision was affected, ask the decision-maker what updated documentation it will accept.
A score increase is not proof that the file is clean. Scores can change for unrelated reasons, and personal identifiers may not directly affect a score while still contributing to future matching problems. The objective is an accurate file and a stable separation of your information from anyone else’s.
When the problem returns or the dispute is rejected
Do not resend the identical one-line dispute indefinitely. Review the response to identify what was verified, what evidence was considered, and whether the company treated the matter as an account dispute rather than a mixed-file problem. Add specific evidence and request the description of the procedure used to determine accuracy and completeness when applicable.
The CFPB explains that consumers may add a brief statement to a file after an unresolved bureau dispute, submit a CFPB complaint, contact a state attorney general, seek legal services, or speak with an attorney. A file statement does not remove wrong information and may not fix an automated decision, so it is a fallback notice rather than the primary remedy.
Legal advice becomes especially important when the error causes a mortgage or housing denial, employment harm, a lawsuit or collection action, repeated reinsertion, disclosure of another person’s information, or substantial financial loss. Deadlines may apply. Preserve adverse-action notices, applications, rates, fees, lost opportunities, and communications rather than trying to reconstruct them later.
Costs, risks, and alternatives
Disputing directly is generally free, as are security freezes and identity-theft recovery resources. The real costs are time, document management, missed opportunities, and the risk of sending sensitive information through insecure channels. Paid credit-repair services do not have a special legal power to make accurate negative information disappear, and no provider can guarantee a score result.
For a straightforward creditor typo, direct contact plus a bureau dispute may be efficient. For confirmed identity theft, the statutory block and recovery plan are more targeted. For a persistent mixed file with serious harm, a consumer-law attorney may be more appropriate than repeated template disputes. The least expensive path is not always the path with the lowest total risk.
A practical 30-day action plan
- Day 1: save all three credit reports and list every unfamiliar item and identifier.
- Day 1: if active fraud is plausible, freeze reports, place an alert, secure accounts, and contact affected institutions.
- Days 2–4: determine whether each item suggests identity theft, mixed matching, a creditor mistake, or a legitimate relationship.
- Days 3–7: collect identity, address, account, and chronology evidence; use IdentityTheft.gov if theft occurred.
- Days 5–10: submit precise disputes or identity-theft block requests through documented channels.
- During the response period: preserve confirmations and answer legitimate requests for missing information.
- After every result: retrieve the actual revised report and compare every field.
- If unresolved: add evidence, request procedure details, submit an appropriate complaint, or obtain legal advice.
Sources and limitations
Primary and authoritative references consulted: Consumer Financial Protection Bureau sample dispute letters and instructions, https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/sample-letters-dispute-credit-report-information/ ; CFPB guidance on unresolved disputes, https://www.consumerfinance.gov/ask-cfpb/what-if-i-disagree-with-the-results-of-my-credit-report-dispute-en-1327/ ; Federal Trade Commission identity-theft guidance, https://consumer.ftc.gov/articles/what-know-about-identity-theft ; the federal recovery portal, https://www.identitytheft.gov/ ; 15 U.S.C. § 1681c-2 on identity-theft blocks, https://www.law.cornell.edu/uscode/text/15/1681c-2 ; 15 U.S.C. § 1681i on reinvestigation procedures, https://www.law.cornell.edu/uscode/text/15/1681i ; and 15 U.S.C. § 1681e on compliance procedures, https://www.law.cornell.edu/uscode/text/15/1681e .
This article is general educational information, not legal, financial, or identity-theft recovery advice for a specific case. Credit-reporting procedures, laws, bureau requirements, and individual facts can change. Verify current instructions with official sources and consult a qualified attorney when rights, deadlines, or material harm are involved.
Build one evidence file before your next move
The strongest response starts with a clean record: the three reports, a list of foreign identifiers and accounts, supporting identity documents, creditor correspondence, and a dated action log. That file helps you choose between a routine dispute, an identity-theft block, and escalation—without making unsupported claims or losing track of what each company changed.
Organize the report before you dispute it
Safesky Digital’s free Credit Repair A-to-Z PDF can help you map unfamiliar items, prepare supporting records and choose your next step without relying on a vague “not mine” claim.
This article is general information, not legal or financial advice. Results vary by credit profile.